How to Budget With AI: A Simple Money Guide
Budget with AI to track spending, plan for rising prices, save for goals and cut costs, with simple prompts, a monthly routine and rules to keep your data safe.
It's the 20th of the month, and you're wondering where your salary went. Rent, food, transport, data, a wedding contribution, a family request, a few small online orders and suddenly there's nothing left. You promise yourself next month will be different. It usually isn't.
Budgeting isn't hard because people are bad with money. It's hard because tracking spending is boring, prices keep changing, and life throws unexpected costs at you. Many people give up after a few weeks of trying to write everything down.
AI can make budgeting far easier. It can turn your bank alerts into a clear picture of your spending, build a realistic budget around your actual life, suggest where to cut, plan for goals and help you adjust when prices rise. This guide shows you how to budget with AI step by step, with prompts you can copy, a simple monthly routine and the rules that keep your financial information safe.
This guide is general information, not financial advice. For major financial decisions, speak to a qualified professional.
What AI Can Do for Your Money
Organise your spending. Turn messy bank alerts and notes into clear categories.
Build a realistic budget. Based on your real income and expenses, not an idealised version.
Find savings. Spot subscriptions you forgot, spending that's crept up and cheaper alternatives.
Plan for goals. Work out how much to save each month for rent, school fees, an emergency fund or a big purchase.
Explain money concepts. Inflation, interest, savings accounts and investment basics, in plain language.
Keep you accountable. A monthly check-in that compares plans to reality.
What AI can't do is know your situation better than you, predict the future or make decisions for you. It's a calculator and coach, not a financial adviser.
Step 1: See Where Your Money Goes
You can't budget without knowing what you actually spend. Start with one month of data.
Gather your transactions. Download your bank statement, or copy your debit alerts for the last month. Add cash spending from memory or notes, and payments from any other accounts or apps you use.
Remove sensitive details. Delete account numbers, card numbers and anything identifying before sharing with an AI tool.
Ask AI to categorise:
Here are my transactions for last month (account details removed): [paste]. Group them
into categories: rent and bills, food and groceries, transport, data and airtime, family
support, savings, eating out, shopping, subscriptions and other. Give me the total per
category, the percentage of my income ([amount]) each takes, and anything that looks
unusual or higher than I might expect.
Review the results. Many people are surprised by small, frequent costs such as transport, snacks, data and delivery fees, which add up quickly.
Step 2: Build a Realistic Budget
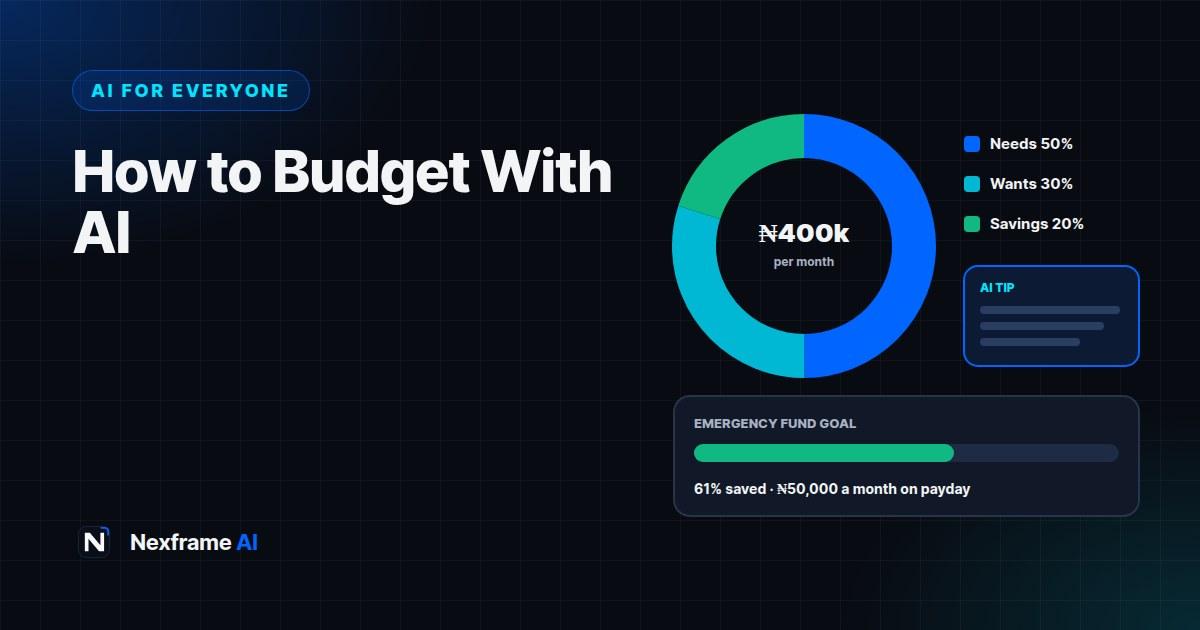
A good budget reflects your real life, including family responsibilities and irregular costs. A simple framework many people start with is splitting income into needs, wants and savings, then adjusting to fit.
My monthly take-home income is [amount]. My fixed costs are [rent, school fees, bills].
Here's last month's spending by category: [paste]. I regularly support family with about
[amount]. My goals are [goals]. Build me a realistic monthly budget with amounts for each
category, including a small buffer for unexpected costs and a savings amount. Explain
any cuts you suggest and keep it achievable, not extreme.
Adjust it until it feels doable. A budget you can follow beats a perfect one you abandon in week two.
Plan for irregular costs
Many budgets fail because of costs that don't happen every month: school fees, rent paid yearly, festive seasons, weddings, birthdays, car repairs and medical bills. Ask AI to help:
These are costs I pay a few times a year: [list with amounts and months]. Work out how
much I should set aside each month so I'm not caught short, and suggest how to keep that
money separate.
Step 3: Plan for Rising Prices
When prices rise quickly, a budget made in January can be wrong by June. Build flexibility in:
Review food and transport costs monthly. These change fastest.
Keep a buffer. Even 5% to 10% of your budget unallocated helps absorb price increases.
Compare and substitute. Ask AI for cheaper meal plans or alternatives:
My family of four spends about [amount] a month on food in [city]. Suggest a weekly meal
plan using affordable Nigerian staples that could reduce this by around 15%, with a
shopping list. Keep meals balanced and realistic.
Buy in bulk carefully. For non-perishables you use often, bulk buying can save money, as long as it doesn't break your monthly budget.
Protect savings from shrinking. Ask AI to explain, in general terms, how inflation affects money held in a regular account and what kinds of options people commonly consider. Then research specific products carefully or speak to a professional before deciding.
Step 4: Cut Costs Without Feeling Deprived
Cutting everything rarely lasts. Focus on changes that save the most with the least pain.
Here's my monthly spending by category: [paste]. Suggest 10 practical ways to cut
spending by [amount] a month, starting with changes that have the biggest impact and
least effect on my quality of life. Include subscriptions to review and ways to reduce
transport and data costs.
Common wins include:
Cancelling subscriptions you rarely use
Switching to a cheaper data plan that matches your actual usage
Cooking more meals at home and planning them in advance
Combining trips to reduce transport costs
Setting a fixed monthly amount for eating out and small treats
Waiting 48 hours before non-essential online purchases
Step 5: Save for Goals
Goals make saving easier, because you know what the money is for. Use AI to make goals concrete:
I want to save [amount] for [goal] by [date]. My current savings for it are [amount].
How much do I need to save each month and each week? Suggest ways to stay on track,
and what I could adjust if I fall behind.
Good goals to start with include:
An emergency fund: often suggested as a few months of essential expenses, built gradually.
Annual costs: rent, school fees or insurance.
A specific purchase: a laptop, a phone or equipment for a side business.
Learning: a course or certification that could raise your income.
Try to move savings automatically into a separate account on payday, so you save first and spend what's left.
A Simple Monthly Money Routine
Spend 30 minutes once a month, ideally a day or two after payday.
Gather last month's transactions and remove sensitive details.
Ask AI to categorise and total them.
Compare with your budget. Where did you overspend or underspend?
Adjust this month's budget for known costs and price changes.
Move savings into your separate account straight away.
Check progress towards your goals.
You can ask AI to guide the review:
Here's my budget and what I actually spent last month: [paste both]. Compare them, tell me
where I went over or under and by how much, suggest three adjustments for this month,
and give me one encouraging insight about what went well.
Add this review to your weekly planning routine. Our guide to planning your week with AI shows how to build regular reviews that stick.
A Worked Example: A Young Professional in Lagos
Bisi earns a monthly salary, pays rent yearly, supports her younger sibling's school fees and wants to start an emergency fund. Every month, she runs out of money before payday.
Spending check: She pastes her anonymised bank alerts into an AI assistant. The categories reveal that transport, food delivery and data take far more than she thought, and she has two subscriptions she forgot about.
Budget: The AI builds a budget that includes a monthly amount set aside for her yearly rent and her sibling's school fees, so these no longer arrive as shocks.
Cuts: She cancels the unused subscriptions, switches to a data plan that matches her actual use and limits food delivery to once a week.
Savings: She sets up an automatic transfer on payday into a separate savings account for her emergency fund.
Monthly review: After three months, her monthly reviews show she's stayed within budget twice and is steadily building her emergency fund. The month she overspent was due to a wedding, which she now plans for in advance.
Keep Your Financial Data Safe
Never share passwords, PINs, card numbers or one-time codes with any AI tool.
Remove account numbers and personal details before pasting statements.
Use official apps only. Be wary of unknown budgeting or loan apps that ask for excessive access to your phone, contacts or messages.
Watch for money scams. Investment schemes promising very high, guaranteed returns are a common scam, increasingly promoted with AI-generated videos. Our guides to spotting AI-generated images and videos and AI voice cloning scams explain the warning signs.
Check privacy settings in your AI tools.
Common Mistakes to Avoid
An unrealistic budget. Extreme cuts don't last. Start with achievable changes.
Ignoring irregular costs. Plan monthly for yearly and seasonal costs.
Forgetting family support. If you regularly help family, include it in your budget.
Saving what's left. Save first, on payday, before spending.
Trusting AI with big decisions. For investments, loans and major commitments, research carefully and get professional advice.
Sharing sensitive data. Remove details before using any AI tool with your finances.
A Sample Budget to Start From
If you've never made a budget, a worked example helps. Here's an illustration for someone taking home ₦400,000 a month, living in a city, with some family responsibilities. Your numbers will differ, so use this only as a starting point.
Rent set-aside (for yearly rent paid in advance): ₦80,000
Food and groceries: ₦90,000
Transport: ₦50,000
Data, airtime and subscriptions: ₦15,000
Utilities and bills: ₦20,000
Family support: ₦40,000
Personal and eating out: ₦30,000
Savings and emergency fund: ₦50,000
Buffer for unexpected costs: ₦25,000
That adds up to ₦400,000. Notice that savings and the buffer are planned in, not left to chance, and that yearly rent is turned into a monthly amount.
Ask AI to adapt it to your life:
Here's a sample budget: [paste]. My take-home pay is [amount], I live in [city], and my
situation is [details, e.g. single, supporting parents, paying school fees]. Adapt this
budget to my situation, keeping savings and a buffer, and explain each change.
Track Spending Without the Effort
The hardest part of budgeting is tracking. Make it as easy as possible:
Use your bank app's insights. Many banking apps now categorise spending automatically. Check them weekly.
Pay digitally where you can. Transfers and card payments leave a record; cash disappears from memory.
Keep a quick cash note. If you spend cash, type a two-word note on your phone, such as "bus 800", and add it to your monthly review.
Use one spending account. Moving money for bills and savings into separate accounts on payday leaves one account for day-to-day spending, which makes it obvious when you're running low.
With these habits, your monthly AI review takes minutes instead of hours.
Final Thoughts
When you budget with AI, the boring parts get faster: categorising spending, building a plan, finding savings and checking progress. What's left is the part that matters, deciding what your money is for.
Start with one month of transactions, build a realistic budget, save first on payday and review monthly. Within a few months, you'll know exactly where your money goes and have more of it left at the end of the month.
If you run a business as well, our guide to AI bookkeeping for small businesses helps you keep business and personal money separate. And if you're looking to grow your income, see our list of no-code AI services you can sell this month.
Frequently Asked Questions
Can AI make a budget for me?
Yes. AI can categorise your spending, suggest a realistic budget and help you review it monthly. You still decide your priorities and make the final choices.
Is it safe to share my bank statement with AI?
Only after removing account numbers, card numbers and personal details. Never share passwords, PINs or one-time codes with any AI tool.
What's the best AI for budgeting?
Any general assistant, such as ChatGPT, Claude or Gemini, works well with your transaction data and a spreadsheet. Choose the one you're most comfortable using.
How do I budget with irregular income?
Base your budget on your lowest typical month, save extra in good months and keep a buffer for lean months. AI can help you plan around income ranges.
How do I budget when prices keep rising?
Review food and transport costs monthly, keep a buffer, compare prices, plan meals and adjust your budget regularly.
Can AI give me investment advice?
AI can explain general concepts, but it isn't a financial adviser. For investment decisions, research carefully and speak to a qualified professional.
How much should I save each month?
It depends on your income, costs and goals. Many people start with a small, consistent amount and increase it over time. AI can help you calculate what's needed for specific goals.
What is an emergency fund?
Money set aside for unexpected costs like medical bills or job loss. It's often recommended to build up a few months of essential expenses gradually.
Comments (0)
Sign in to post a comment.
- Be the first to comment.